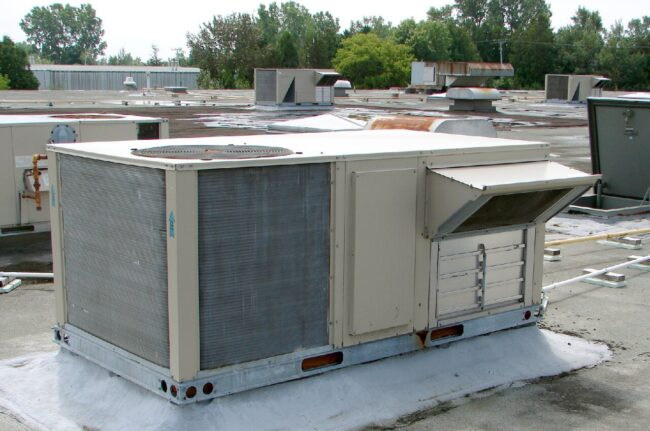
Rooftop packaged air-conditioning and heating units. Photo: P199 via Wikimedia Commons, public domain.
Quick Answer: Miami-based Watsco reported record third-quarter 2026 revenue of $2.22 billion, up 7%, as residential HVAC equipment sales rose 7%. But gross margin fell to 26.4% from 27.5%, and diluted EPS dropped 5% to $3.77. Watsco also closed two acquisitions that add 107 locations and about $730 million in annual revenue.
Watsco is one of Florida’s least familiar large public companies. From its Miami headquarters, it runs a network of 804 locations that distribute air conditioning, heating and refrigeration equipment, along with parts and supplies, to the contractors who install and repair HVAC systems. Its customers are the technicians who show up when a home’s air conditioner fails in August.
Watsco released its third-quarter 2026 results on October 27. The report showed a company growing sales again after a difficult transition to new refrigerant products, while giving up some margin to win that volume. It also showed Watsco doubling down on two strategies that have defined it for decades: buying regional distributors and investing heavily in technology. This analysis covers each part of the report.
What did Watsco report for the third quarter of 2026?
Revenue rose 7% to a record $2,220.4 million from $2,067.0 million a year earlier. Same-store sales, which exclude recently acquired locations, grew 4%. Gross profit rose 3% to $586.3 million.
Profitability declined. Gross margin was 26.4%, down from 27.5%, and selling, general and administrative expenses rose 8% to $370.7 million, or 5% on a same-store basis. Operating income fell 4% to $225.2 million, and operating margin narrowed to 10.1% from 11.4%. Net income attributable to Watsco was $155.4 million, compared with $161.6 million, and diluted earnings per share fell 5% to $3.77 from $3.98.
Chairman and Chief Executive Officer Albert H. Nahmad struck an upbeat tone: “Third quarter results and early fourth quarter sales trends are indicative of continued improvement in end-market demand.” On the earnings call, he added, “Demand trends are now normalizing, organic growth is improving,” according to StockStory.
The share count also rose slightly, which reduced per-share results. Weighted-average diluted shares were about 38.6 million in the quarter, compared with about 37.9 million a year earlier, so net income spread across more shares produced a larger percentage decline in EPS than in net income.
Watsco Q3 2026 at a glance
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $2,220.4M | $2,067.0M | +7% |
| Same-store sales growth | +4% | n/a | n/a |
| Gross profit | $586.3M | $568.9M | +3% |
| Gross margin | 26.4% | 27.5% | -110 bp |
| SG&A | $370.7M | $343.7M | +8% |
| Operating income | $225.2M | $234.8M | -4% |
| Operating margin | 10.1% | 11.4% | -130 bp |
| Net income attributable to Watsco | $155.4M | $161.6M | -4% |
| Diluted EPS | $3.77 | $3.98 | -5% |
| Operating cash flow | $325M | $355M | -8% |
Source: Watsco Form 8-K, Exhibit 99.1, October 27, 2026.
How did the results compare with expectations?
Revenue was slightly ahead of Wall Street estimates, but earnings fell short. Finviz reported that the $3.77 EPS compared with a consensus estimate of $4.13, a miss of about 7%, while revenue of $2.22 billion topped the $2.21 billion consensus. StockStory reported that the shares, which entered the report at $305.33, traded at $292.49 afterward, a decline of about 4%.
The quarter did show improvement from earlier in 2026. Same-store sales grew 4%, up from 1% in the second quarter. Operating margin of 10.1% was below the 11.2% Watsco posted in the second quarter, however, and gross margin of 26.4% compared with 28% for full-year 2025.
Watsco 2026 trend
| Measure | Q2 2026 | Q3 2026 |
|---|---|---|
| Same-store sales growth | +1% | +4% |
| Operating margin | 11.2% | 10.1% |
| EPS vs. consensus | n/a | $3.77 vs. $4.13 |
Sources: Watsco release; Finviz; StockStory.
Which product lines are growing?
HVAC equipment makes up 67% of Watsco’s sales, excluding acquisitions, and grew 5% in the quarter. Within that, residential equipment sales rose 7%, driven by 5% unit growth and a 2% increase in average selling price. Commercial equipment sales fell 5%.
Other HVAC products, which include parts, supplies and accessories and account for 29% of sales, grew 2%. Commercial refrigeration, the smallest category at 4% of sales, grew fastest at 10% in the quarter and 14% year to date.
Watsco sales by category, excluding acquisitions
| Category | Share of sales | Q3 2026 growth | Nine-month growth |
|---|---|---|---|
| HVAC equipment | 67% | +5% | +2% |
| Residential equipment | Part of HVAC equipment | +7% | +4% |
| Commercial equipment | Part of HVAC equipment | -5% | -4% |
| Other HVAC products | 29% | +2% | +1% |
| Commercial refrigeration | 4% | +10% | +14% |
Source: Watsco Q3 2026 earnings release.
The return of residential unit growth is the most important signal in the report. Watsco said residential demand is stabilizing “following the prior year transition to new A2L products,” referring to the industry’s shift to a new class of lower-global-warming-potential refrigerants. That transition disrupted ordering patterns and pricing in 2025, and the company said residential unit volumes have now returned to growth.
Why did Watsco’s margins shrink?
Watsco attributed the decline in gross margin to several factors: customer mix, the mix between replacement sales and new residential construction, and smaller price increases from equipment manufacturers in 2026 than in 2025. When manufacturers raise prices, distributors holding inventory bought at lower prices can earn extra margin as they sell it. Smaller manufacturer price increases this year mean less of that benefit.
Management said the third-quarter margin is more in line with historical seasonality, and that the year-to-date margin reflects current market conditions. For the first nine months, gross margin was 27.2%, down from 28.3%.
According to Finviz’s account of the call, management also cited customer mix shifting toward larger accounts, residential new construction growing faster than replacement, equipment outgrowing higher-margin products, the comparison against last year’s refrigerant shortage, and dilution from the lower-margin Jackson Supply business. Management acknowledged that industry unit volumes remain 10% to 15% below levels of two years ago and that consumer affordability is a concern.
Florida featured directly in the discussion. Residential new construction had slowed in Florida and Texas in the second quarter, according to Finviz, and in the third quarter residential new construction grew in the low double digits.
Watsco has not given up on higher margins. A.J. Nahmad set a long-term goal of 30% gross margin, supported by digital platforms and changing contractor behavior, according to StockStory. Chief Financial Officer Barry Logan pointed to “a more ordinary and conventional” pricing environment ahead, while noting that cost structure and customer mix could keep margins fluctuating. Finviz noted that expected 2027 manufacturer price increases tied to metal and freight inflation could help restore margin.
Higher operating costs added to the pressure. SG&A grew 8% in the quarter, faster than revenue, partly because 30 new and acquired locations were included. On a same-store basis, SG&A rose 5%, close to the 4% same-store sales growth.
How did Watsco perform over the first nine months?
Year-to-date results show a smaller increase in revenue and a larger decline in earnings than the quarter alone. Revenue rose 3% to $5,858.2 million, while gross profit fell 1% to $1,592.8 million. Operating income fell 7% to $573.8 million, and diluted EPS fell 7% to $9.72 from $10.48.
Cash generation improved sharply. Operating cash flow for the nine months was $303.7 million, up 79% from $169.8 million a year earlier.
Watsco nine-month results
| Metric | 9M 2026 | 9M 2025 | Change |
|---|---|---|---|
| Revenue | $5,858.2M | $5,660.5M | +3% |
| Gross profit | $1,592.8M | $1,602.0M | -1% |
| Gross margin | 27.2% | 28.3% | -110 bp |
| Operating income | $573.8M | $618.8M | -7% |
| Operating margin | 9.8% | 10.9% | -110 bp |
| Net income attributable to Watsco | $397.8M | $425.2M | -6% |
| Diluted EPS | $9.72 | $10.48 | -7% |
| Operating cash flow | $303.7M | $169.8M | +79% |
What acquisitions did Watsco make?
Watsco grows in part by buying established regional distributors and integrating them while keeping their existing leadership and connecting them to its technology platforms, according to StockStory’s summary of the earnings call. It has completed 74 acquisitions since entering distribution in 1989. Two deals in 2026 are among its larger recent additions.
In June, Watsco acquired Jackson Supply Company, founded in 1972, with about $230 million in annual sales, 25 locations and about 5,000 customers in Sunbelt markets. Jackson Supply’s third-quarter sales were $78 million, up 16% from a year earlier.
In October, Watsco acquired The Granite Group, founded in 1971, with about $500 million in annual sales, 82 locations and about 11,000 customers in the Northeast. It is Watsco’s fourth acquisition of a dual-trade business that sells both HVAC and plumbing products. Watsco now has 112 locations that offer both.
Together, the two companies add 107 locations and about $730 million in annualized revenue, which Watsco expects to increase its annual revenue by about 10%.
Watsco’s 2026 acquisitions
| Company | Founded | Annual sales | Locations | Customers | Region | Closed |
|---|---|---|---|---|---|---|
| Jackson Supply Company | 1972 | About $230M | 25 | About 5,000 | Sunbelt | June 2026 |
| The Granite Group | 1971 | About $500M | 82 | About 11,000 | Northeast | October 2026 |
| Combined | n/a | About $730M | 107 | About 16,000 | n/a | n/a |
Source: Watsco Q3 2026 earnings release.
How is Watsco using technology and AI?
Watsco has spent years building digital tools for contractors, and the numbers are now substantial. E-commerce sales grew 10% in the third quarter and 12% for the nine months, and reached $2.75 billion over the trailing 12 months, or 37% of revenue. More than 73,000 contractors and technicians engage with Watsco digitally.
OnCallAir, Watsco’s platform that lets contractors build and present equipment quotes to homeowners, generated $1.6 billion of gross merchandise value in the first nine months, up 14%, and $2.0 billion over the trailing 12 months from about 351,000 quotes.
The company has invested about $280 million in technology over five years and currently spends about $64 million a year. Its newer tools include Ask.Watsco, an internal AI tool with more than 2,700 users, and a customer-facing AI tool, as well as SupplySync, a platform for institutional customers that launched as a pilot. President A.J. Nahmad said, “Our focus remains on advancing these unique capabilities – with AI enabling better and faster speed to market.”
Watsco digital metrics
| Measure | Figure |
|---|---|
| E-commerce sales, trailing 12 months | $2.75 billion (37% of revenue) |
| E-commerce growth, Q3 / nine months | +10% / +12% |
| OnCallAir GMV, trailing 12 months | $2.0 billion, up 14% |
| OnCallAir quotes, trailing 12 months | About 351,000 |
| Contractors and technicians engaged digitally | More than 73,000 |
| Technology investment, five years | About $280 million |
| Internal AI tool users | More than 2,700 |
What about inventory?
Inventory is a key item to watch. Finviz reported that Watsco’s inventory rose $397 million in the third quarter, even though management had said earlier that inventory peaked in the second quarter, offset partly by a $383 million increase in payables. The Granite Group acquisition adds another $140 million to $150 million of inventory. For a distributor, inventory ties up cash, but it also positions the company to serve contractors during peak season and ahead of manufacturer price increases.
How strong is Watsco’s balance sheet?
Watsco’s balance sheet is conservative. At September 30, it had $498.7 million in cash and equivalents plus $150 million in short-term investments, and its balance sheet showed no borrowings line. In October it signed a new five-year, $750 million unsecured revolving credit facility.
Watsco shareholders’ equity was $3,029.1 million, and total equity including non-controlling interests was $3,535.5 million, against total assets of $5,233.8 million.
The dividend is central to Watsco’s identity. The company raised its annual dividend 10% in April 2026 to $13.20 per share and has paid dividends for 52 consecutive years. It paid $392.0 million in dividends during the first nine months. Watsco says it has delivered a 17% compounded annual total shareholder return since it entered distribution in 1989.
Brian’s Take
When I was analyzing stocks, the companies I respected most were the ones that kept compounding quietly, year after year, without a lot of noise. Watsco fits that description. Fifty-two straight years of dividends, 74 acquisitions, no borrowings on the balance sheet, and a business built around a product Floridians cannot live without.
This quarter is a mixed one on the surface. Revenue hit a record and residential unit volume grew 5%, but margins slipped and earnings per share fell 5%. To me, the more important trend is that demand is recovering after the refrigerant transition, and Watsco just bought two businesses that should add about 10% to revenue.
The technology numbers also stand out. Thirty-seven percent of revenue through e-commerce is a lot for a distributor that sells to contractors. That is a Miami company quietly building one of the most digital distribution businesses in its industry.
Frequently Asked Questions
Where is Watsco headquartered?
Watsco is headquartered in Miami, Florida, and operates 804 locations.
What were Watsco’s Q3 2026 results?
Revenue rose 7% to a record $2.22 billion, with same-store sales up 4%. Diluted EPS fell 5% to $3.77 as gross margin declined to 26.4%.
Why did Watsco’s margin decline?
Watsco cited customer mix, the balance of replacement and new construction sales, and smaller manufacturer price increases in 2026 than in 2025.
What acquisitions did Watsco complete in 2026?
Jackson Supply Company in June and The Granite Group in October, adding 107 locations and about $730 million in annual revenue.
How much is Watsco’s dividend?
Watsco pays $13.20 per share annually after a 10% increase in April 2026, and has paid dividends for 52 consecutive years.
Sources and Further Reading
- Watsco, Inc., Third Quarter 2026 Results, Form 8-K Exhibit 99.1, October 27, 2026 – U.S. Securities and Exchange Commission
- Finviz, “Watsco Misses as Margin Erosion Overwhelms a Real Volume Recovery,” October 2026
- StockStory, “WSO Q3 Deep Dive: Margin Compression Amid Growth and Technology Investment,” October 2026
- PHCP Pros, “Watsco Reports Record Third Quarter Sales,” October 2026
About Brian French
Led by a commitment to tech-intelligent curation, Brian French tracks and analyzes the corporate developments defining Florida's economy. Brian brings an extensive financial background to his analysis, having graduated from the University of South Florida in Finance and serving as a Vice President and Portfolio Manager for Merrill Lynch Private Investors and the Trust Department in St. Petersburg, FL, as well as a Vice President and Trust Investment Officer for SunTrust Bank in Sarasota, FL. His writing blends macroeconomic trends, fiduciary capital markets, corporate strategy, and modern digital insights for a sophisticated look at Florida's business market.